
Business & Civil Legal Services | U.S. Legal Explainer
Understand when a lawyer can evaluate deceptive sales, disputed debts, identity misuse, and consumer remedies.
Choosing legal representation for consumer protection is easier when the issue is divided into decisions instead of marketing claims. The attorney’s work depends on the facts, jurisdiction, available documents, the other people or organizations involved, and the outcome the person actually needs. This guide explains the moving parts without claiming that one legal strategy fits every case in the United States.
The topics below move from the first signs of a legal problem to evidence, procedural choices, and the practical questions to ask before signing an engagement. They are written for readers who want to understand a professional service, not for people seeking a substitute for advice based on a confidential review of their particular circumstances. State law, venue, contract wording, and filing dates can all alter the analysis.
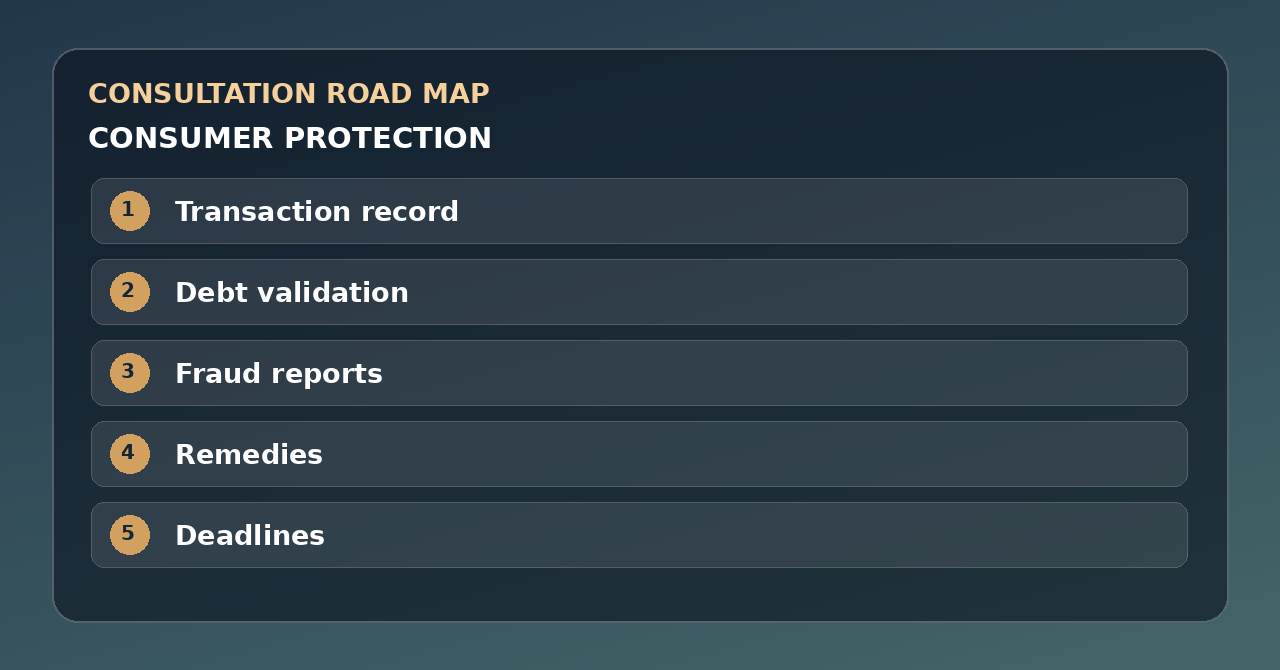
For business & civil legal services, an effective first conversation often produces a narrower, more useful question than “Can I win?” It should clarify which facts are established, which claims or obligations are still disputed, what records matter, what action cannot wait, and who is responsible for the next step. Use the five-part decision map as a navigation aid rather than a scorecard predicting results.
Begin with the disputed transaction
A consumer protection lawyer reviews who sold the product or service, what representations were made, what the contract says, how payment occurred, and what failed to happen. A bad customer-service experience is not always a statutory violation. The precise marketing claim, omission, billing practice, or collection conduct determines the legal analysis.
Ask the prospective lawyer to demonstrate how begin with the disputed transaction fits into the specific consumer protection decision, what they would examine first, and what finding would prompt a change of course. Their answer should acknowledge that a short initial meeting cannot substitute for reviewing the actual evidence.
Deceptive sales evidence
Save advertisements, checkout screens, refund policies, receipts, emails, screenshots with context, and contemporaneous messages. Online pages may change after a sale, so preserving the original wording matters. Counsel considers whether a representation was material and how it relates to actual consumer injury under applicable law.
For this stage, keep the debt validation question distinct from the broader dispute. Ask whether the service being offered covers investigation, document preparation, negotiation, and appearances, or only selected tasks. A written scope prevents misunderstandings when the work expands.
Debt-collection rights
The federal Fair Debt Collection Practices Act regulates covered debt collectors and certain practices, alongside other consumer rules. Validation information and dispute procedures can help a person assess whether a claimed debt is accurate. The consumer should distinguish a collector from the original creditor and note that state laws may provide additional protections.
Before acting on advice about debt-collection rights, ask what is a binding requirement and what is merely a recommended practice. Counsel should distinguish the two, note whose authorization is needed, and flag any step that might permanently narrow the available options.
Identity theft requires rapid coordination
Unexpected accounts or collection notices may justify contacting financial institutions, preserving records, checking credit reports, and using official identity-theft resources. A lawyer may help when inaccurate information persists or legal proceedings arise. Never send full identification documents to a caller solely because they claim to be fixing fraud.
In a case involving consumer protection, the timing of this decision can be as important as its substance. Request the next material deadline, the form of notice or filing that applies, and a sensible contingency if a record or third-party response arrives later than expected.
Resolving billing disputes
Credit-card disputes, recurring subscriptions, financing charges, and service contracts may follow separate procedures. Preserve the dates of statements and disputes. A lawyer compares available chargeback rights, statutory remedies, arbitration provisions, and the contract’s own cancellation language before suggesting a strategy.
Compare two plausible approaches to resolving billing disputes: a narrowly scoped early action and a more resource-intensive review. Have the lawyer explain what additional information the larger effort could provide and why that information is worth its cost in these circumstances.
Class actions are not the default
A widespread practice may lead to aggregated litigation in some circumstances, but certification and adequacy standards are complex. An individual claim may be more suitable for small claims, agency complaints, direct negotiation, or a different forum. Counsel should explain whether joining a group action affects individual rights.
Before agreeing to the proposed transaction record task, identify who will prepare it, what the client must supply, and what counts as a satisfactory result. A well-defined deliverable is especially useful when several professionals work on different pieces of the matter.
Agency reports have a purpose
FTC, CFPB, state attorneys general, and sector regulators may accept reports within their authority. A complaint can help identify patterns but is not necessarily a personalized recovery service. Keep confirmation numbers and do not assume submission automatically pauses a court deadline or debt collection process.
The sensible question is not whether agency reports have a purpose sounds important in the abstract. It is whether a particular legal or factual uncertainty justifies immediate attention, and what consequence follows if that uncertainty is left unresolved during the next phase.
Fee arrangements and remedy size
Some consumer statutes allow attorney-fee recovery in qualifying cases, while others do not. Ask about eligibility, expense risk, settlement approval, confidentiality, and whether the agreement includes appeals. Evaluate the realistic benefit of pursuing a claim against the time and effort it may require.
If fee arrangements and remedy size becomes contested, ask how the attorney would explain the issue to a decision-maker who has never met the parties. Organizing the supporting facts in that order can reveal missing documents and identify assertions that still need independent verification.
Red flags when hiring help
Be cautious of anyone promising to erase accurate debt, instantly repair every credit report, or obtain guaranteed compensation without reviewing evidence. Verify license status and demand a clear written scope. A credible lawyer distinguishes what the facts support from what the consumer understandably hopes happened.
An intake conversation about red flags when hiring help should end with a decision owner, a realistic timeframe, and a method for reporting changes. This turns a broad professional promise into a practical working arrangement the client can understand and monitor.
A realistic example: how the pieces connect
Illustrative scenario—not an account of an actual client or legal outcome. A buyer pays for an annual online service after viewing a cancellation promise, then discovers recurring charges despite documented cancellation attempts. Counsel reviews the original checkout representation, payment statements, customer-service record, and governing agreement. The adviser compares direct resolution, a card dispute, and any applicable consumer remedy rather than assuming every subscription dispute warrants a class action.
The useful lesson for a reader researching consumer protection is to identify exactly where professional judgment is required. One professional may need to interpret documents, another may supply technical facts, and a court, agency, or contracting party may ultimately control the result. A good attorney can specify which questions are answerable today and which remain conditional without overstating certainty.
Preparing for the first attorney consultation
Use the following working file to make an initial conversation more productive. It is not a substitute for any court form, government instruction, or document request your adviser actually provides.
- Transaction record. Create a brief, date-ordered note about transaction record. Separate things personally observed from information relayed by someone else, and identify where an original record can be found.
- Debt validation. For debt validation, list documents already held, documents another party controls, and any information that might not remain available indefinitely. Record an authorized way to request or preserve it.
- Fraud reports. Write down what a successful near-term decision about fraud reports would actually look like. Do not assume that the best outcome is necessarily a courtroom judgment or a large payment.
- Remedies. Explain the practical constraints affecting remedies: available time, work obligations, cash flow, family responsibilities, privacy concerns, and any existing legal order or contractual duty.
- Deadlines. Ask who handles deadlines within the engagement, what it costs, how progress is communicated, and whether a change in circumstances requires a separate agreement or outside specialist.
Comparing counsel without relying on marketing promises
Interviewing two or more qualified lawyers can expose useful differences in experience, staffing, scope, and communication. Ask for a plain-language explanation of the proposed work concerning consumer protection, a copy of the written fee arrangement, and an estimate of foreseeable expenses that are not part of the basic charge. An advertisement describing an impressive past result is not a reliable forecast of how an unrelated matter will end.
Verify the attorney’s eligibility to practice in the appropriate jurisdiction, potential conflicts, and who would personally handle the file. For business & civil legal services, expertise is not interchangeable across every specialty: distinguish licensing, local procedure, negotiation, litigation, and any necessary technical or administrative knowledge. If the issue involves an imminent filing date or safety concern, emphasize prompt, jurisdiction-specific help rather than prolonged comparison shopping.
Frequently asked questions
Can the FTC recover my money directly?
Reporting may help regulators, but it is not a guarantee of individual reimbursement. Your situation may require further review of local procedures and original documents.
Does a collection notice mean the debt is valid?
No. Review the provided validation information and dispute rights. Ask the professional which assumptions in that answer depend on the actual record.
Should I pay a stranger to fix identity theft?
Start with official channels and independently verified institutions. A reliable next step is to confirm the governing rule before signing or filing anything.
Are cancellation clauses always enforceable?
Their validity depends on terms and applicable consumer law. Written scope and timelines can help prevent confusion about what assistance is included.
Can I sue without hiring a lawyer?
Some forums permit self-representation, but costs and procedural rules still matter. If a deadline is approaching, seek individualized help rather than waiting for an online answer.
Bottom line for consumer protection
Start with the actual issue, a truthful chronology, and the documents that can substantiate it. Compare legal help based on relevant experience, a clear scope, transparent financial terms, and how the professional explains uncertainty. The strongest first step is often to preserve an option and improve the quality of the information available for the next decision—not to assume the most dramatic outcome is inevitable.